A Reversal That Isn’t Resolving
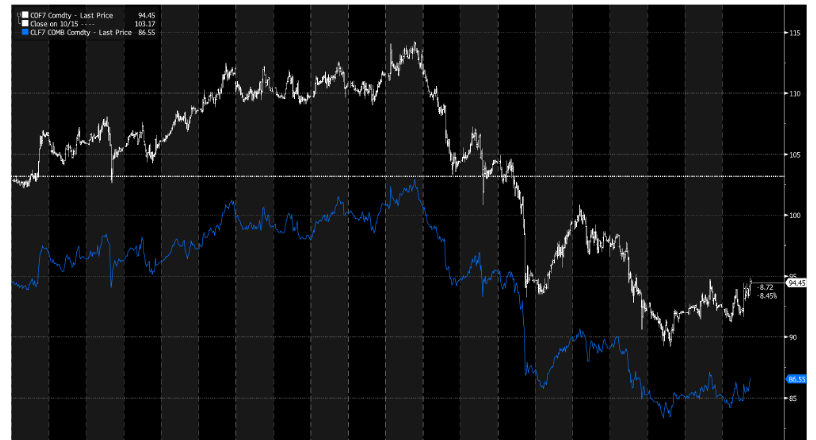
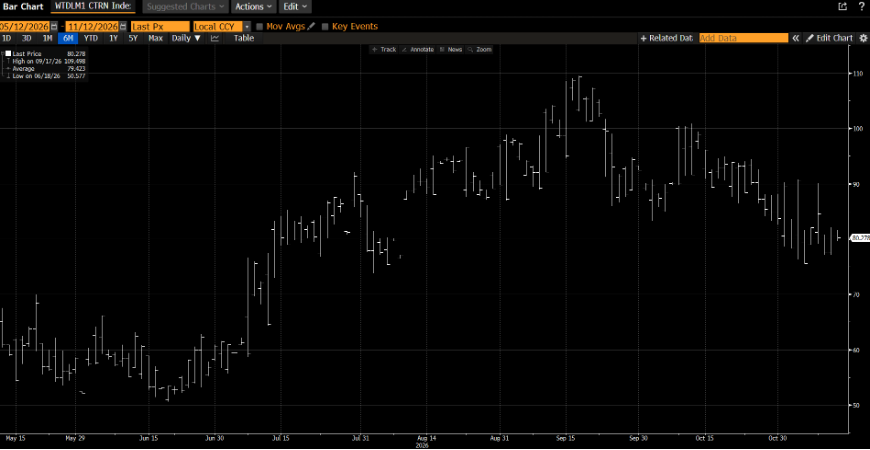
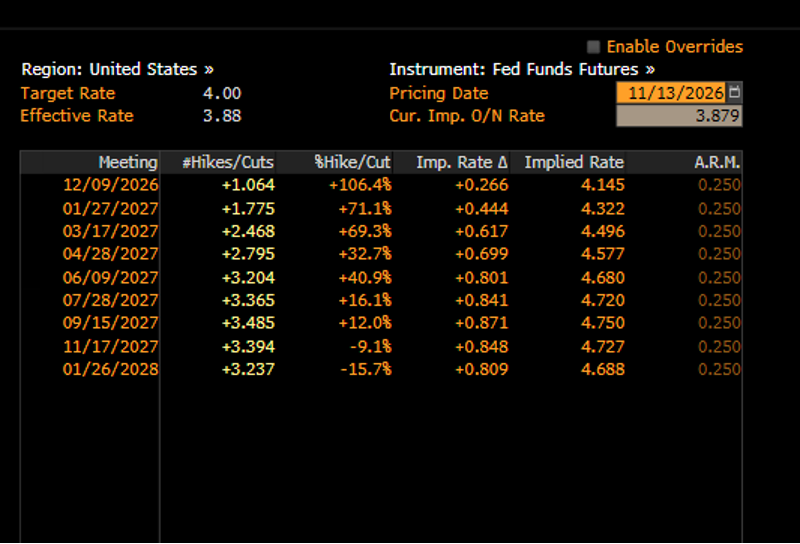
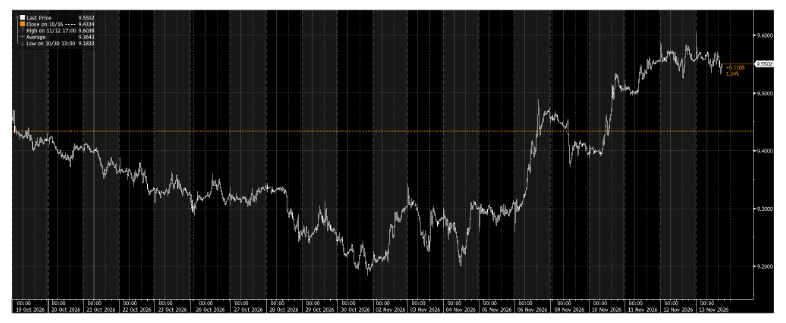
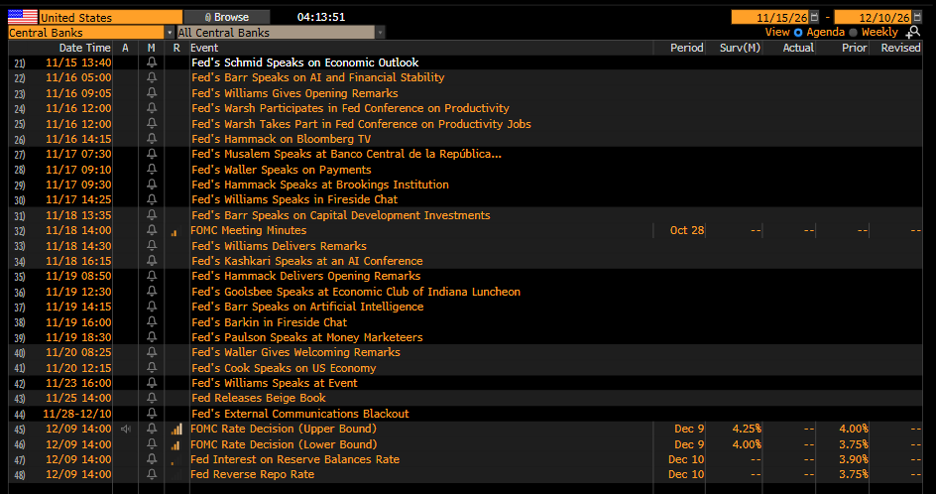
Oil is down sharply since late October. Diesel isn’t. That divergence, rather than the headline crude price on which most of the commentary is fixated on, is potentially the real story behind this month’s inflation surprise and the Fed’s sudden lurch toward a December hike.
The crude move itself looks like classic de-escalation trading rather than anything structural. Brent and WTI have both fallen more than 8% from their October 15 closes, with the US president publicly pushing back against resuming strikes on Iran even as Iran’s security chief has threatened retaliation against US bases. With few positive signs of a resolution, the market is signaling that it has decided, for now, to stop pricing in the worst case.
Supply has reinforced the move: Aramco cut its Arab Light price to Asia to a six-year low for November cargoes as Gulf producers chase market share and Hormuz flows recover. Markets are treating this as a ceiling coming off, not a floor giving way, and that distinction could matter for how durable the relief turns out to be.